

Airtable’s acquisition by Bending Spoons for $1.285Bn EV ($2.25Bn equity value) quickly became the defining Silicon Valley story of the week, primarily because the headline numbers forced the tech community to confront a sobering reality about software valuations:


As a ZIRP-era VC SaaS darling, Airtable had reached an $11.7Bn valuation in 2021, making the acquisition’s peak-to-exit valuation reset especially significant.
As of June 2026, Airtable was at ~$480M ARR (+20% YoY), posting strong SaaS metrics including ~90% gross margins and 170% NDR. These are solid fundamentals, and yet Airtable sold for 2.7x ARR. For comparison, the average EMCloud company currently trades around 7.6x EV/current ARR while growing at a similar rate.
Airtable raised ~$1.4Bn in total funding over its history. The company was not in distress and, in fact, had close to a billion dollars of cash on the balance sheet, meaning it had runway (time!) and resources to shape its future.
Beyond the deal numbers, perhaps the most interesting detail was what wasn’t included in the acquisition. Airtable’s Hyperagent (AI agent platform) was carved out prior to the transaction, indicating that Bending Spoons mainly acquired Airtable’s incumbent SaaS business. I’ll return to this Hyperagent discussion a little later.
Airtable’s acquisition has already generated plenty of discourse across the broader tech community, so rather than gratuitously adding to the noise, I’ll focus on unpacking two lessons:
I. The writing has been on the wall for this valuation recalibration
Back in 2023, I warned about the post-ZIRP era valuation hangover and how a reckoning was inevitable given the significant disconnect between inflated private software market valuations and a recalibrated public market paradigm. These worlds would need to converge eventually.
Some startups attempted to outrun valuation recalibration through unnatural means, such as taking “dirty term sheets”, to hold on to last round marks, but this merely kicked the can down the road. 2026’s SaaSpocolypse then made the pressure impossible to ignore. As capital, customers, and talent shifted toward AI-native software, incumbent SaaS companies faced another blow: multiples cratered across the industry as investors began questioning the very durability of what had long been considered a highly predictable business model.
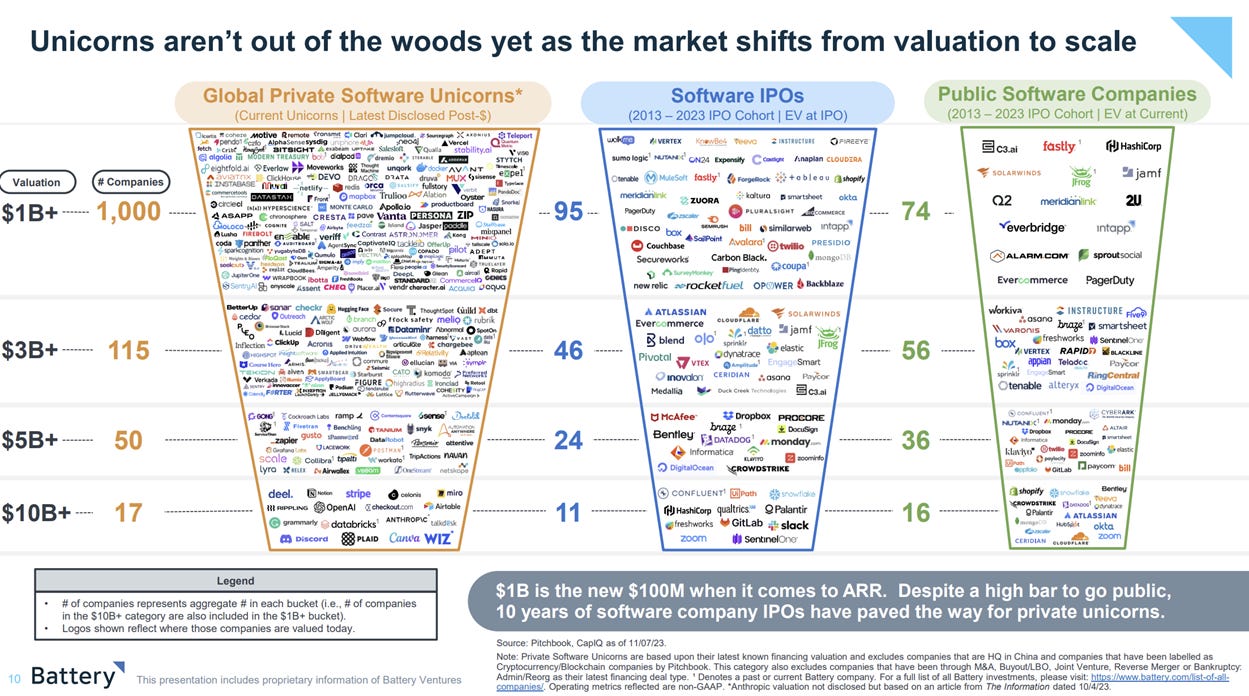
Airtable is likely just the first high-profile canary in the coal mine. I anticipate more casualties ahead, particularly among the large cohort of “mispriced” private software unicorns (exhibit above) trapped in what I call the “Schrödinger’s Startup Paradox”: companies whose last funding round reflects a valuation that no longer exists, yet whose true market value remains unknown until they are forced to transact.
II. Sometimes burning the boats is what it takes to move forward
I’ve written previously about the AI-related drivers impacting the fate of SaaS incumbents. As with any tech cycle, some incumbents will become extinct, but not every incumbent is doomed. Some will successfully reinvent themselves by leveraging existing distribution, proprietary data, customer trust, and workflow ownership to launch compelling AI products and reaccelerate growth through AI Second Acts. My colleagues and I at Bessemer refer to these “reborn” incumbents as Phoenixes.
Phoenixes are very rare. In my view, an incumbent’s AI rebirth is almost never about market forces or product/technology alone. It often comes down to leadership. Most incumbent CEOs stay in a defensive posture, protecting the past. Counterintuitively, Phoenix leaders do the complete opposite: they go on offense, reject the Innovator’s Dilemma, and disrupt themselves before someone else does it for them. They don’t just gently steer their company toward AI transformation; in extreme cases, they take radical action to sacrifice today’s success for tomorrow’s opportunity.
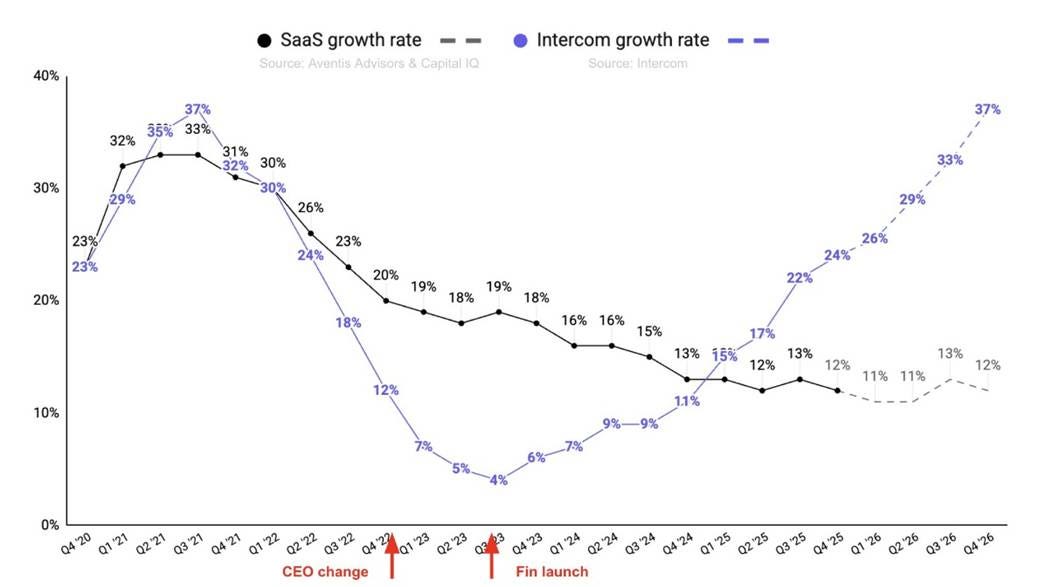
Few leaders embody this Phoenix mindset better than Eoghan McCabe of Fin/Intercom, a Bessemer portfolio company that pulled off an AI rebirth (chart above) and recently announced its $3.6Bn acquisition by Salesforce. This reflection from McCabe perfectly captures both the difficulty and the opportunity ahead for incumbent software founders:
“To my peers in software: This shit is insanely hard. (And if it’s not hard it’s unlikely you’re doing it right.) The shift from on-prem to cloud wrecked many companies, but the change was not nearly as fast. And while it proved quite difficult for the previous generation to adapt quickly enough to keep up with my own, the shift in approach, skillset, go-to-market, and more was not nearly as dramatic. But, still, this shift is possible. Little, old, left-for-dead 15 year old Intercom did it. You can do it too! You have the brand, the customer base, the cashflows, and the access to debt. And you have the workflow tools that can be adapted for their new future for use alongside your agents too. Most of you have started moving towards this world already, but in contrast to what most AI-pilled technologists believe, I don’t think it’s too late if you haven’t! The tech is moving so fast, but customer adoption in many places will remain slow. Many large software companies will die and be bought for parts, but many will survive. As someone who’s been grinding alongside you for decades in this industry, I know how scary this time is. I want you to survive it and win. All it will take is destroying everything you love.”
This brings us back to Airtable’s Hyperagent spin-out from the legacy platform. Airtable had been dabbling with an AI pivot for over a year now, but had not shown growth reacceleration despite several new AI product launches, AI-pilled hires, and AI-native acquisitions. Incremental moves weren’t cutting it, so more drastic action was needed. Regardless of how you view the acquisition economics, I believe Airtable’s leadership deserves credit for making a bold call to embrace disruption instead of defending the status quo.
Whether Hyperagent ultimately becomes a Phoenix story remains to be seen. But it points to a broader lesson for software incumbents: succeeding in the AI era may require not just a pivot, but a full "bend" away from the past. Or as McCabe puts it, “the only path to success in the future is through destroying your past”.
The Hyperagent carve-out is the detail that actually matters here, not the 2.7x multiple. Bending Spoons bought the mature business and let the founders keep the thing with real optionality, which tells you what both sides think the AI product is worth right now versus later. The "Schrödinger's Startup Paradox" line is going to age well, there have to be dozens of companies sitting on 2021 marks that just haven't been forced to open the box yet. Which do you think produces the next forced marking, more SaaS incumbents, or the AI-native darlings that raised at their own nosebleed multiples?
That price is rough next to the old valuation. Airtable was still growing about 20% and the deal came in near 2.7 times ARR. I’m curious how many other software companies would see the same reset if a buyer showed up.